Flyte Aviation Reports Record Q3 2026 Revenue of $1.838 Million, Up 145% Sequentially
Why It MattersSmall Part 135 operators that scale on owned aircraft can grow quickly, but thin cash and dependence on lessor-supplied jets leave their results tied to delivery timing and financing.
What happened
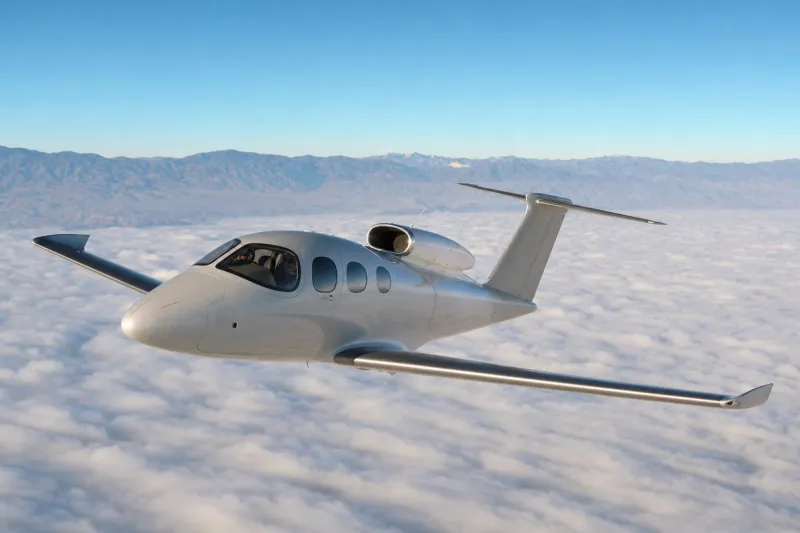
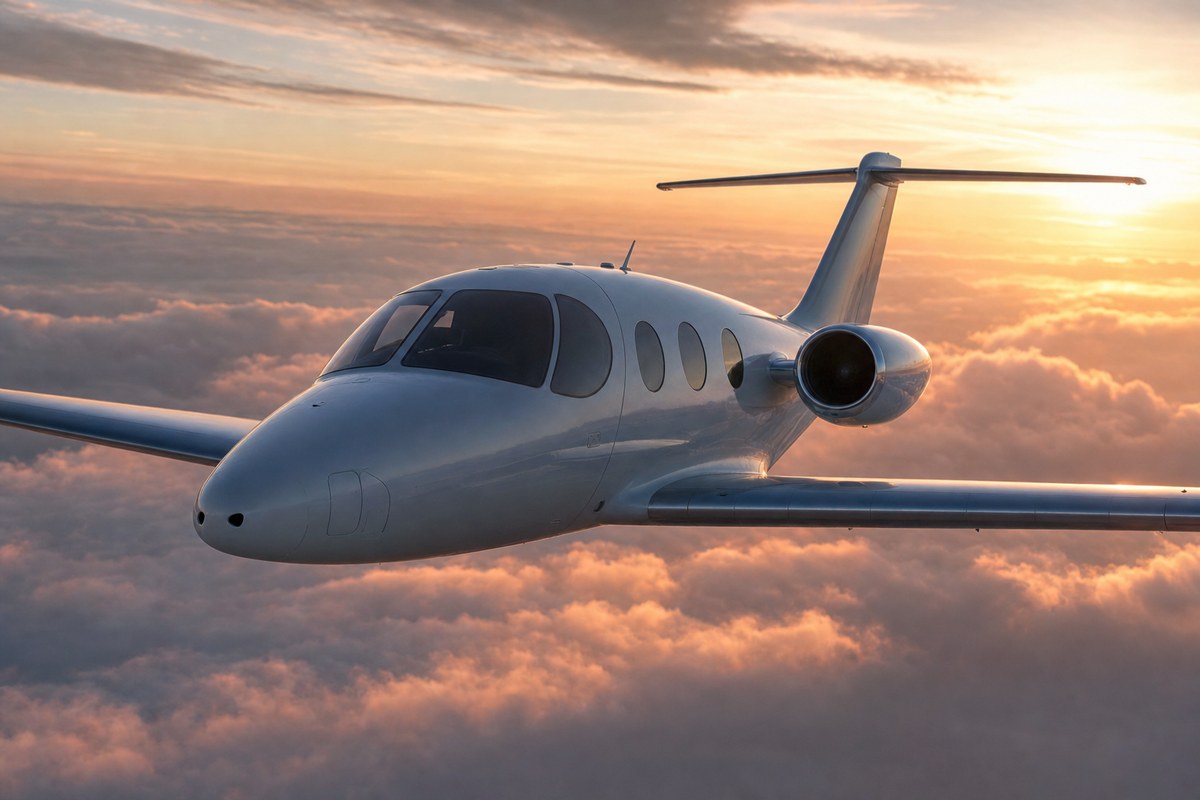
Flyte Aviation, Inc. (NYSE American: VJET), a Cirrus Vision Jet operator, reported record quarterly revenue of $1,838,000 for the quarter ended September 30, 2026, a 145% sequential increase. Total flight hours rose 129% sequentially, driven by higher demand and the addition of two aircraft to the fleet. More than 99% of customer flights were flown on the company's own fleet rather than on third-party charters, and time flown per leg averaged 52 minutes.
For the third quarter, Flyte reported a net loss of $15.1 million, which includes a $13.3 million non-cash impairment charge on the MedTech assets held for sale. The loss from continuing operations was $1.9 million. Cash and cash equivalents were $2.4 million as of September 30, 2026, and the detailed results are filed with the SEC on Form 10-Q. Flyte operates through its FAA-certified Part 135 subsidiary, Ponderosa Air, LLC.
Three more aircraft are being added to the fleet. All three have completed the lessor's pre-purchase inspections and are expected to join the fleet and begin revenue flights during the December quarter. The company is hiring and qualifying additional pilots for the new jets and expects to add more aircraft in the first half of 2027 and beyond.
Canada and the MedTech sale
In October, Flyte received its Foreign Air Operator Certificate and Transport License, had its Canadian tariff filed and accepted, and flew its first Canadian flights. The company already serves markets including the Bahamas and the Caribbean.
The company classified its legacy MedTech segment as held for sale and its results as discontinued operations in September 2026. MedTech revenue rose 4% sequentially and 24% year-over-year to $280,000. On November 1, 2026, Flyte signed a non-binding letter of intent to sell the segment. Completion remains subject to due diligence, a definitive agreement, approvals, third-party consents and other closing conditions, and there is no assurance a transaction will be completed.
Industry impact & what to watch
Flyte's quarter shows how a small single-type jet operator grows: new aircraft arrive, flight hours follow, and revenue rises faster than the underlying base because the starting point is small. Flying more than 99% of customer legs on its own fleet means the revenue is tied to aircraft and pilots the company controls, so growth depends on how quickly lessor-supplied jets clear inspection and crews qualify to fly them.
The gap between $1.9 million lost from continuing operations and a $15.1 million net loss is mostly the non-cash MedTech charge, which separates the flying business from the legacy segment being exited. Against that, cash of $2.4 million is a small cushion for a fleet scheduled to grow by three aircraft this quarter and more in the first half of 2027.
The next milestones are the three aircraft beginning revenue flights in the December quarter and whether the non-binding MedTech letter of intent converts into a definitive agreement. Sustained Canadian flying, now that the certificate and tariff are in place, would show whether the cross-border addition adds volume beyond the Bahamas and the Caribbean.