McKinsey: Ageing Business Jet Fleet Could Trigger New Capacity Shortage as Deliveries Remain Below 2008 Peak
Why It MattersFleet growth driven by deferred retirements rather than new output means supply depends on aircraft that are now reaching major checks, so tight capacity looks structural for the segment.
What happened
McKinsey has warned that the global business aviation industry could face another wave of capacity shortages as older private jets approach major maintenance milestones or retirement, while limited new aircraft production makes replacement difficult. The report said supply constraints and rising maintenance needs could further tighten availability in a market where demand has kept growing since the COVID-19 pandemic.
Manufacturers delivered 842 business jets in 2025, about 65 per cent of the 2008 peak of 1,290. The global fleet grew by 730 aircraft last year, largely because fewer planes were retired rather than because production rose significantly. Retirements fell from around 300 in 2019 to about 110 in 2025, while deliveries rose from around 810 to roughly 840 over the same period. McKinsey said older aircraft returning to service helped operators meet the post-pandemic demand surge, but many of them could soon reach major maintenance milestones and be retired.
Activity continues to expand. Global business jet departures grew by an average of 4.9 per cent a year between 2019 and 2025, reaching a record 3.9 million last year, and the average aircraft flew about 19 per cent more hours in 2025 than in 2019. Limited hangar and parking space, maintenance capacity and skilled personnel are adding pressure. NetJets Aviation President Patrick Gallagher said, as cited in the report, that infrastructure is by far the biggest challenge the company contends with.
McKinsey said these constraints make direct aircraft ownership harder and push customers toward fractional ownership, charter and jet cards. The number of aircraft in fractional ownership fleets rose from 990 in 2019 to 1,510 in 2025, and their share of total business jet flight hours increased from 14 per cent to 20 per cent.
Industry impact & what to watch
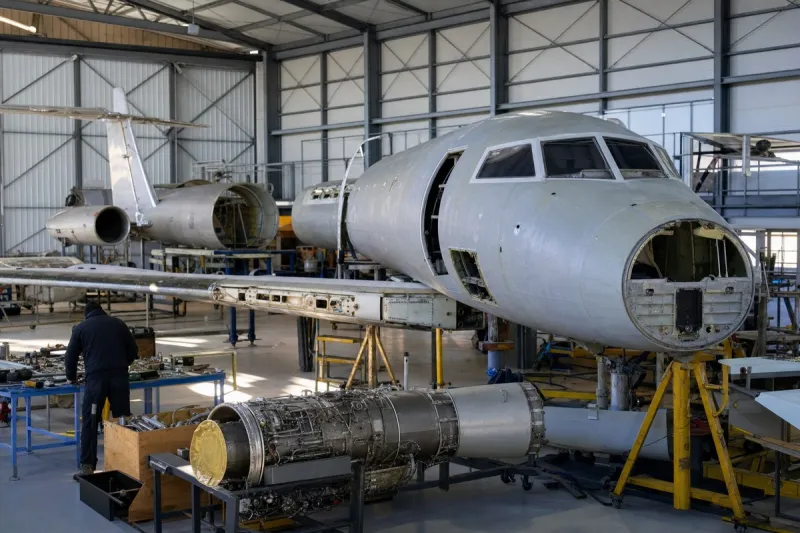
The figures describe a fleet that has been stretched rather than renewed. With deliveries still well under the 2008 level and retirements suppressed, the recent growth in aircraft count rests on keeping older airframes flying. That is a one-time cushion: once those aircraft reach heavy checks, owners face a choice between a costly overhaul and retirement, and either path removes or sidelines lift at the same moment demand is still climbing.
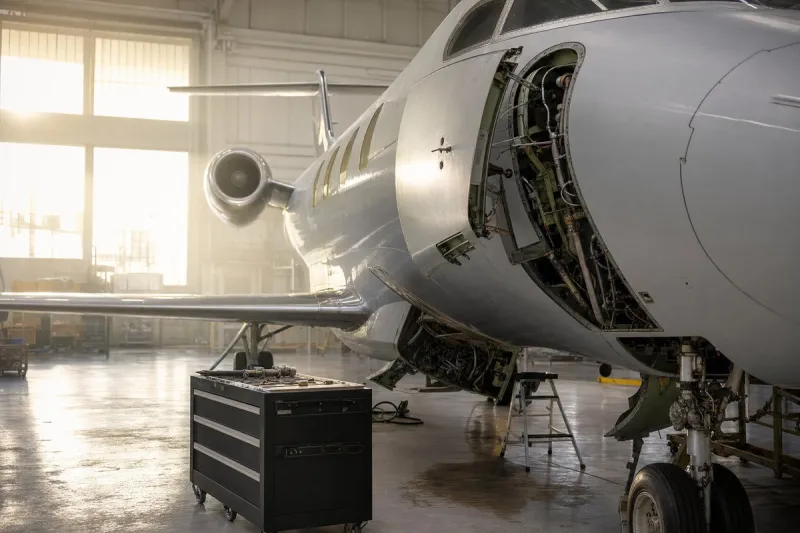
For maintenance providers the report points to a demand shift that is structural rather than cyclical. An older fleet needs more work per aircraft, and overhaul capacity is already tight, so hangar slots, skilled technicians and parts become the constraint that sets how much of the fleet is actually available to fly.
The same squeeze explains the drift toward fractional ownership, charter and jet cards, where operators with scale can lock in capacity, maintenance access and infrastructure that individual owners struggle to secure. McKinsey expects further consolidation as companies seek that scale. The next signal is whether delivery volumes climb meaningfully above the 842 recorded in 2025, or whether retirements begin to rise from the 2025 level of about 110.