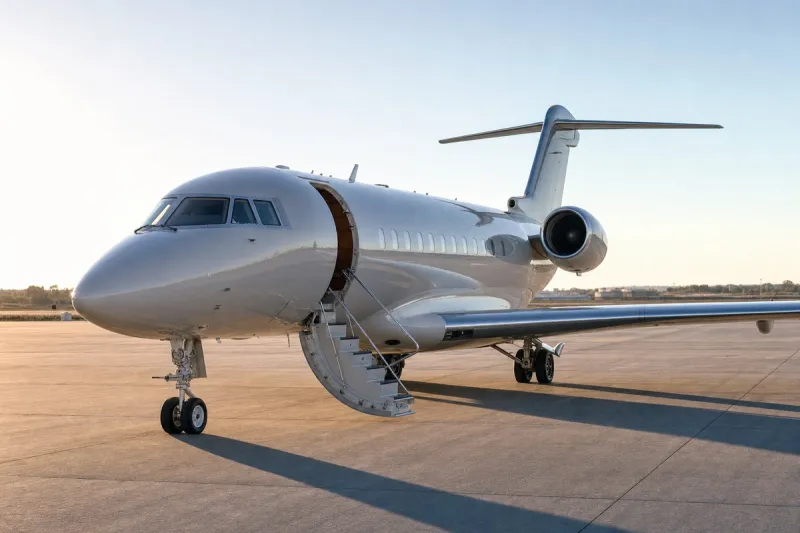
McKinsey Report: Business Aviation Hits Record 3.9 Million Departures in 2025, Driven by Leisure Flying and Fractional Growth
Why It MattersGrowth now hinges on securing scarce aircraft, crews, maintenance slots and airport access, which favors the largest fractional and managed fleets and pushes the segment toward consolidation.
What happened
McKinsey & Company has published its inaugural State of Business Aviation in 2026, concluding that business aviation keeps growing despite constraints on aircraft availability, airport infrastructure, maintenance capacity and rising operating costs. The report draws on industry data and executive interviews. It says securing an aircraft is now only part of the challenge: operators must also line up pilots, maintenance support, hangar space and airport access.
Citing WingX data, McKinsey says global private aviation flight hours returned to pre-pandemic levels by March 2021, nearly three years before commercial airlines fully recovered. Departures have risen an average of 4.9% annually since 2019, reaching a record 3.9 million in 2025. Total flight hours increased from 4.7 million in 2019 to 6.4 million in 2025, a 37% gain. North America accounted for 70% of global flight hours in 2025, although Latin America and Asia-Pacific grew faster in percentage terms.
Fractional ownership was the fastest-growing operating model. Fractional fleets grew from 990 aircraft in 2019 to 1,510 in 2025, or 7.3% annually, and fractional operators' share of business jet flight hours rose from 14% to 20%. NetJets and Flexjet accounted for 92% of fractional flight hours excluding turboprops. Charter's share slipped from 19% to 18%, third-party aircraft management held 25%, and corporate and private flight departments fell from 36% to 30%.
Private jet departures at U.S. leisure airports grew 5.4% annually between 2019 and 2025, versus 2.1% at traditional business destinations. Leisure airports accounted for 326,000 of the 417,000 additional U.S. departures in that period, while Chicago Midway, Oakland and Van Nuys saw declines. NetJets Aviation President Patrick Gallagher said destinations including Naples, Scottsdale, Jackson Hole and Bozeman are increasingly busy year-round as second-home owners travel more often.
Manufacturers delivered 842 business jets in 2025, compared with the industry record of 1,290 in 2008. Annual retirements fell from about 300 in 2019 to 110 in 2025. Between 2019 and 2025, very light jet fleets grew 6.7% annually and long-range fleets 5.1%, and 65% of ultra-long-range jet flights departing the United States covered less than 1,000 nautical miles. NetJets, Flexjet and VistaJet together accounted for about 20% of global business jet flight hours in 2025, up from 15% in 2019.
Where the demand is landing
The geography of growth has shifted toward places people go to live rather than places they go to work. Leisure airports supplied 326,000 of the 417,000 additional U.S. departures between 2019 and 2025, while three traditional metro-area fields lost traffic. For FBOs and handlers, that means peak-season congestion at second-home destinations is becoming a year-round condition, which is the pressure Gallagher describes at Naples, Scottsdale, Jackson Hole and Bozeman.
The fleet data point the same way. With 842 deliveries in 2025 against a 2008 record of 1,290, and retirements down to about 110 a year, the installed base grew largely because operators kept older aircraft flying. That sustains maintenance demand and keeps pilots, hangar space and shop slots as binding as the airframes themselves.
Industry impact & what to watch
The mix of who flies is moving toward scale operators. Fractional programs took share from flight departments, and the three largest global brands lifted their combined share of business jet flight hours from 15% to about 20%. When aircraft and crews are scarce, buyers who want guaranteed access tend to move to programs that already hold the fleet, the pilots and the maintenance relationships. That is the mechanism behind the consolidation McKinsey expects, and it explains why charter's share slipped slightly even as total flying rose.
The constraint is also changing what counts as a competitive asset. Aircraft alone no longer confer advantage when delivery volumes sit well below the 2008 peak and the fleet is aging in place. Crew pipelines, maintenance capacity and ground access at busy leisure airports are now the scarce inputs, and they are slow to add. Operators with them can absorb the growth; operators without them face rising costs for the same flying.
McKinsey points to artificial intelligence, improved scheduling, predictive maintenance and fewer empty-leg flights as the efficiency levers available. Whether those gains offset tighter supply is the open question the report itself leaves to operators, and the next few years of delivery and retirement figures will show how much room the fleet has to grow.