Wheels Up Q3 Revenue Falls 11% to $164.8M as Signature Fleet Takes Majority of Flight Revenue; Orders Six Phenom 300E, Gets $100M Delta Credit Line
Why It MattersWheels Up's shift from a legacy fleet and memberships to a premium Phenom and Challenger Signature model shows a major fractional-style operator trading near-term revenue for a more profitable, uniform fleet.
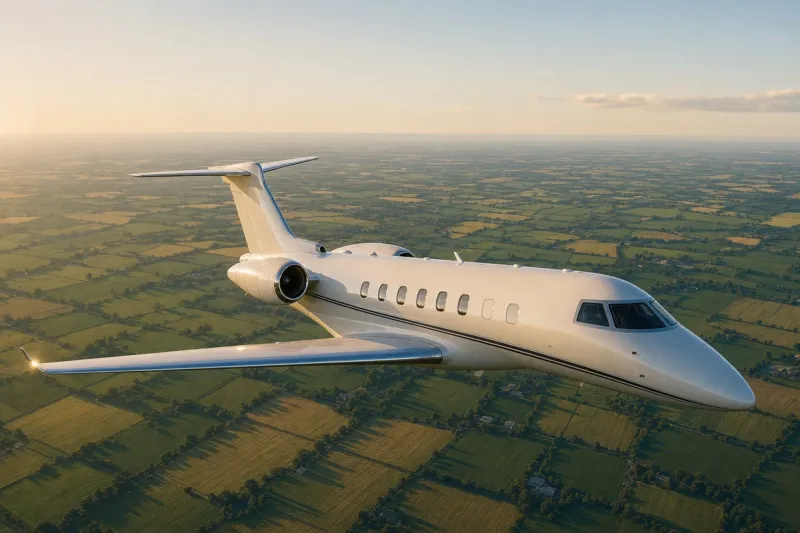
Wheels Up Experience Inc. (NYSE:UP) reported third-quarter 2026 results on Nov. 5, 2026. GAAP revenue was $164.8 million, down 11% year over year, about 3 points of which came from the disposition of non-core services businesses in the third quarter of 2025. Private Jet Flight revenue was $143.9 million, down 7%. Revenue from the premium Phenom and Challenger fleet rose 120%, outpacing 79% fleet growth from 24 to 43 aircraft, while legacy fleet revenue fell 44% as the company winds down its legacy programs.
Gross profit was $15.2 million, a $16 million improvement from a year earlier, and was affected by about $3 million of business transformation-related expenses. Net loss was $89.4 million, or $(2.48) per share, about $6 million larger than a year earlier. Adjusted Contribution was $27.0 million, up 15%, with an Adjusted Contribution Margin of 16.4% versus 12.7% a year earlier. The company estimated about 3 points of year-over-year margin pressure, roughly 1 point from the prior-year sale of non-core services businesses and roughly 2 points from transitory inefficiencies of the transformation.
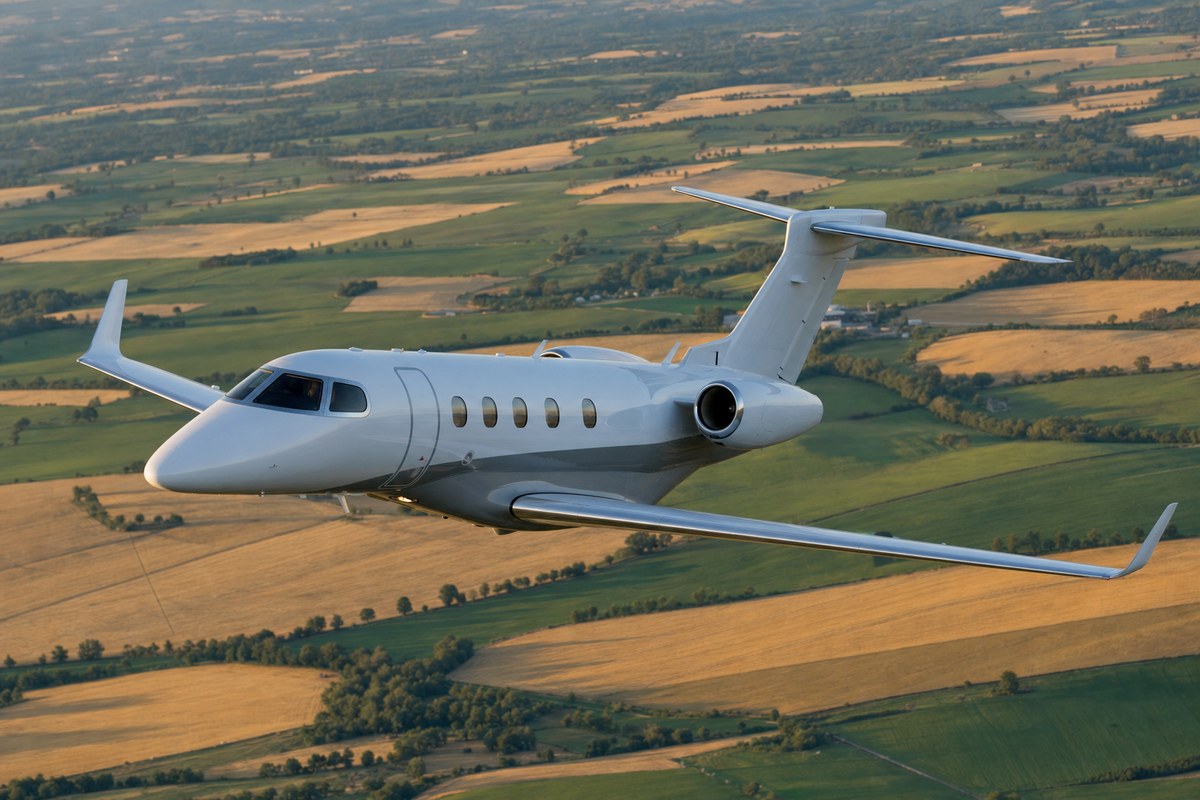
Wheels Up announced an order for six factory-new Embraer Phenom 300E aircraft, expected to be delivered in the third and fourth quarters of 2027. Delta Air Lines committed an additional $100 million revolving credit facility to the company. The Signature Membership program has grown to more than 1,500 members, up 130% year to date through September, while legacy memberships fell 62% after the April announcement of the wind-down of legacy programs and fleet. Signature revenue and memberships surpassed legacy revenue and memberships for the first time.
Operationally, the Completion Rate was 99.3%, up about 1 point, and On-Time Performance (A-30) was 86.4%, up nearly 4 points. Through the end of September 2026 the company recorded 163 Brand Days, meaning days with a perfect Completion Rate and no operational cancellations. Wheels Up ranked sixth among U.S. airlines in the 2026 Condé Nast Traveler Readers' Choice Awards, launched a refreshed brand campaign, The Right Way to Fly, in early October, and in September named an enhanced Sustainable Aviation Fuel program its primary sustainability offering, replacing carbon offsetting.
For the nine-month period, net loss was $279.6 million versus $265.3 million a year earlier, Adjusted EBITDA was a loss of $75.6 million (improved by $13.2 million), Adjusted EBITDAR was a loss of $53.9 million (improved by $22.0 million), and net cash used in operating activities was $208.3 million versus $147.9 million. CEO George Mattson said the company's 2027 focus is completing the sunset of legacy membership programs and scaling the Signature Membership.