eVTOL Ultra-Fast Charging Battery Market Estimated at USD 3.82 Million in 2025, Forecast to Reach USD 28.45 Million by 2034
Why It MattersRevenue in this niche tracks aircraft certification calendars, so flight-test pack orders that vanish after design changes are separate from the recurring spare-pack and scaled-manufacturing demand that certification can unlock.
What happened
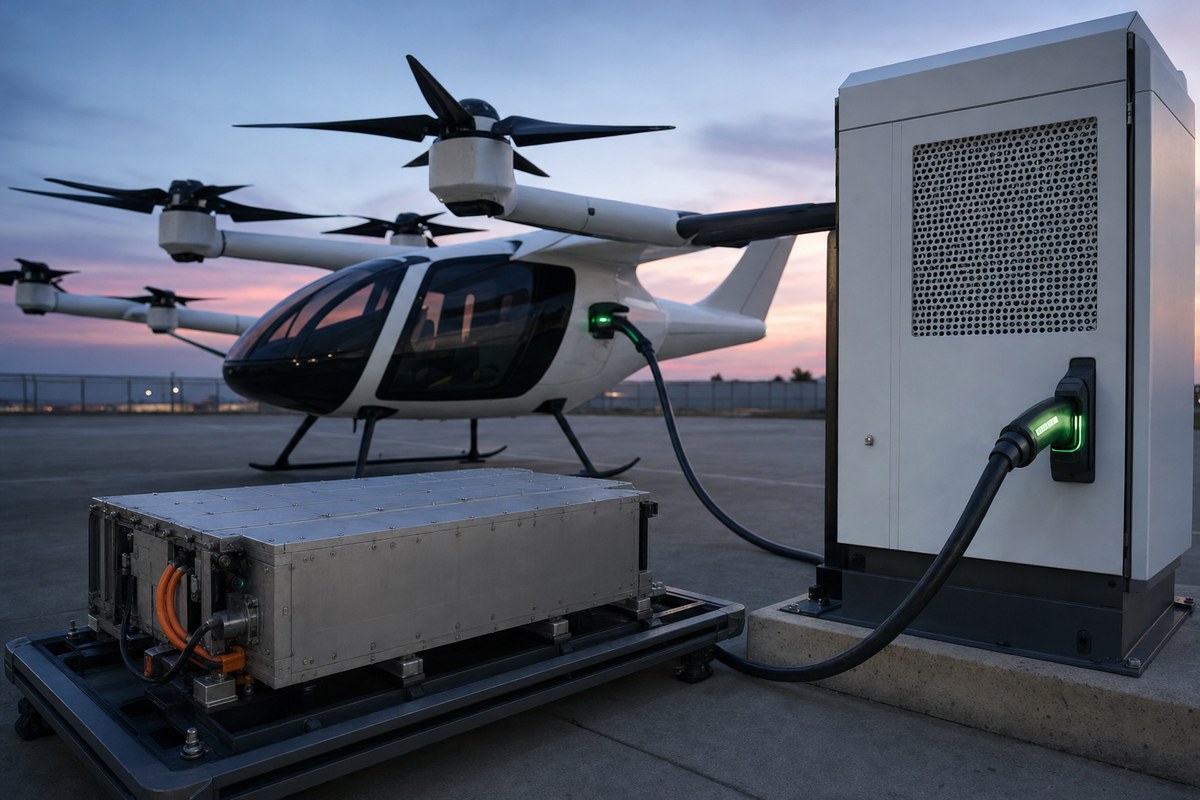
The global eVTOL ultra-fast charging battery market reached an estimated USD 3.82 million in 2025, with a 2026 outlook of USD 4.77 million and a forecast of USD 28.45 million by 2034. That corresponds to a 25.0% CAGR during 2026–2034. The revenue boundary covers first-sale aviation propulsion battery packs and pilot pack assemblies engineered to accept unusually high charging power between eVTOL missions.
Asia-Pacific is the largest region with an estimated 67% of 2025 revenue, followed by North America at an estimated 15%. Ternary high-nickel lithium packs lead by chemistry with an estimated 58% share in 2025, and passenger air taxi and sightseeing programmes lead by mission with an estimated 66% share.
EHang reported 221 eVTOL aircraft deliveries for full-year 2025; that figure is not a count of ultra-fast battery packs. EHang and Greater Bay Technology agreed in April 2024 to develop aviation packs targeting a charge from 30% to 80% in five to ten minutes, with pack density above 200 Wh/kg. CATL reported in 2026 a passenger eVTOL battery system using prismatic cells at 350 Wh/kg that passed a no-propagation thermal verification test and was prepared for initial use on AutoFlight aircraft.
In Europe, Vertical Aerospace has developed battery systems at its UK Vertical Energy Centre. In March 2026 it reported a pilot production line intended to build packs for seven Valo certification aircraft, and its 2025 annual filing describes a 200 Wh/kg pack performance target and rapid turnaround between missions.
Industry impact & what to watch
A market sized in single-digit millions is, in practice, a handful of programme-linked purchases rather than a volume business. The headline CAGR is applied to a very small base, so the 2034 figure of USD 28.45 million still describes a niche supply chain tied to a short list of aircraft programmes.
The report ties early demand to aircraft certification calendars. Flight-test fleets may need several pack configurations that never turn into recurring replacement orders if a programme changes design, whereas certification can open demand for spare packs and scaled manufacturing. For a battery supplier, revenue timing therefore depends on the airframer's regulatory progress as much as on cell chemistry. EASA special conditions and means-of-compliance consultations shape the validation work Vertical Aerospace and others must complete.
The report also separates development agreements from delivered commercial packs and says development revenue should not be combined with finished-pack revenue. The EHang and Greater Bay Technology targets of a 30% to 80% charge in five to ten minutes are programme objectives, not a market-wide standard. Pilot production runs such as the seven-aircraft Valo line are an early milestone for judging whether that distinction narrows.