Fractional Share Resale Value Can Swing Hourly Cost by Hundreds of Dollars, BizJet Journal Model Shows
Why It MattersFractional proposals that look cheaper on hourly operating rates can cost more once resale value is counted, so exit-value assumptions and buyback wording shape true ownership economics across the segment.
What happened
BizJet Journal published an analysis on October 28, 2026 arguing that the value recovered when a fractional aircraft share is sold changes the cost of every hour flown, and should be weighed alongside operating rates when comparing fractional ownership proposals.
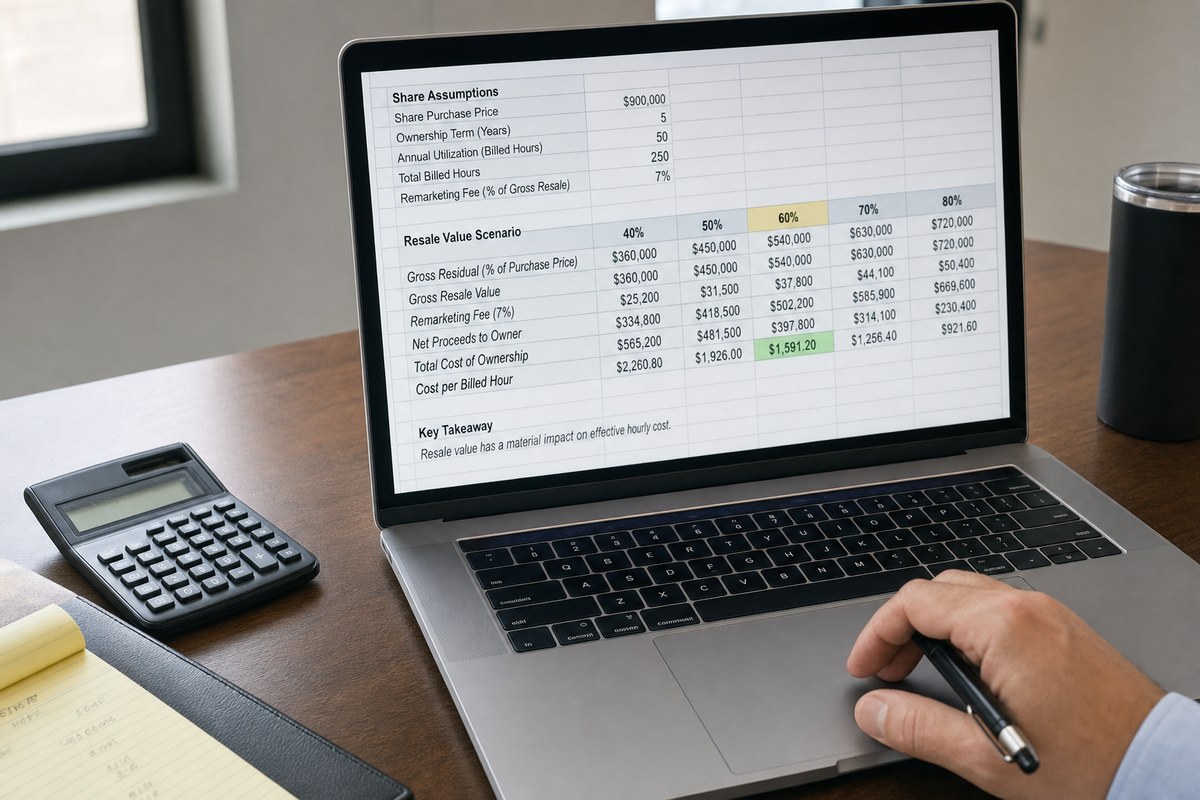
The model assumes a $900,000 share held for five years, with 50 billed hours used per year (250 in total) and a remarketing fee of 7% of gross resale value. At a 60% gross residual, gross resale value is $540,000, the fee is $37,800 and net proceeds are $502,200. Capital consumed is $397,800, or 44.2% of the purchase price, which works out to $1,591.20 per billed hour before operating expenses. Applying the 7% fee to the original $900,000 purchase price rather than to resale value would give $63,000 instead of $37,800, overstating selling costs by $25,200.
Holding purchase price, fee and hours constant, each ten-percentage-point change in gross residual value moves five-year cost by $83,700, or $334.80 per billed hour. Gross residual assumptions of 40%, 50%, 60%, 70% and 80% produce capital costs per billed hour of $2,260.80, $1,926.00, $1,591.20, $1,256.40 and $921.60. The difference between the 40% and 80% cases is $334,800. A competing proposal saving $200 per billed hour on operating charges would be more than offset by a ten-point weaker residual.
Buyback terms and depreciation
NetJets describes its liquidity arrangement as fair market value on 90 days' notice, without promising a set percentage of purchase price. flyExclusive's 2025 annual report describes repurchase value as the aircraft's fair market value multiplied by the ownership percentage, less a remarketing fee. Flexjet lists a 1/16 share as providing 50 annual hours with a maximum term of 60 months; the purchase price, residual percentage and fee in the model are model inputs, not a Flexjet proposal.
The analysis separates market depreciation (change in what the aircraft or share would sell for), book depreciation (an accounting expense) and tax depreciation (deductions affecting taxable income). Adding a separate depreciation expense to a purchase-minus-sale calculation counts the loss twice, and there is no universal annual depreciation rate. In its second-quarter 2026 market report, AMSTAT reported business jet median values up 5% year over year while asking-price measures declined.
Utilization and tax treatment
A fractional owner's 50-hour allocation does not limit the hours accumulated on the aircraft the owner partly owns, since other owners and positioning also add use. NBAA's fractional ownership FAQ notes that an agreed residual-value method may or may not account for high utilization, so contractual and independent appraisal values can differ.
On tax, the analysis cites IRS guidance dated January 14, 2026 on 100% additional first-year depreciation for eligible property acquired after January 19, 2025, and IRS Publication 946 qualified-business-use tests (more than 50% and a separate 25% test). In its example, full immediate deduction of $900,000 at a 30% effective rate would cut the initial tax bill by $270,000. A deduction is not reimbursement of the purchase price, and IRS Publication 544 depreciation recapture rules can apply on sale.
Industry impact & what to watch
Fractional programs are usually compared on purchase price, monthly management fees and hourly operating rates, because those figures sit in the proposal. The resale leg is the one number nobody can quote with certainty, yet in this model it moves cost by $334.80 per billed hour for every ten points of residual. That is larger than the $200 operating-rate difference used as the competing-proposal example, which means a buyer can pick the cheaper-looking contract and still pay more per hour of flying.
Because the program contracts cited tie repurchase to fair market value less a remarketing fee, rather than to a guaranteed share of the purchase price, the residual is a market outcome that the buyer carries. How that fair market value is determined, and whether high accumulated aircraft hours enter the appraisal, therefore decides what the exit leg is worth, and independent appraisals can differ from contractual values.
The tax angle works the same way: an accelerated deduction changes the timing of tax paid, not the economics of the aircraft, and recapture rules can pull value back at sale. Comparing proposals on a consistent basis, with residual assumptions, fee base and utilization stated side by side, is what the model's sensitivity table is built to enable.