GCC Business Jet Market Led by Foreign Manufacturers, With No Japanese Makers Listed
Why It MattersRegional business aviation is organised around Western airframers and Gulf-based operators and MRO providers, so access for smaller national fleets tends to come through international service networks rather than domestic manufacturing.
What happened
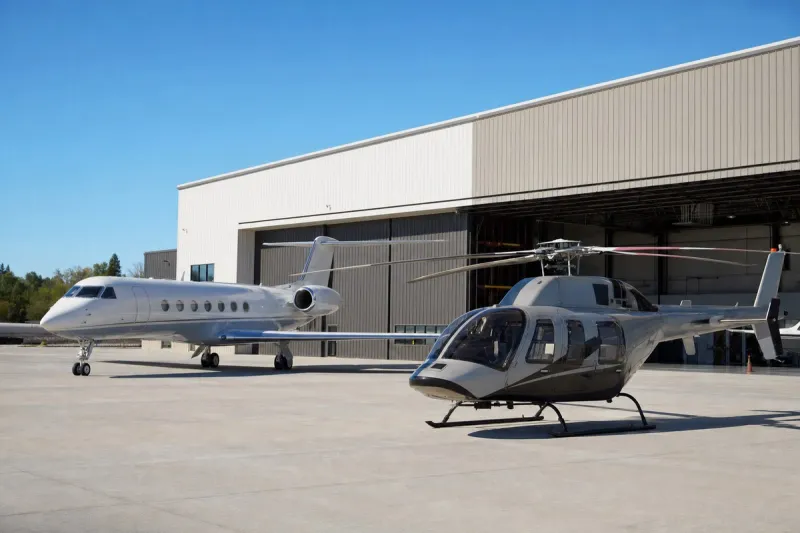
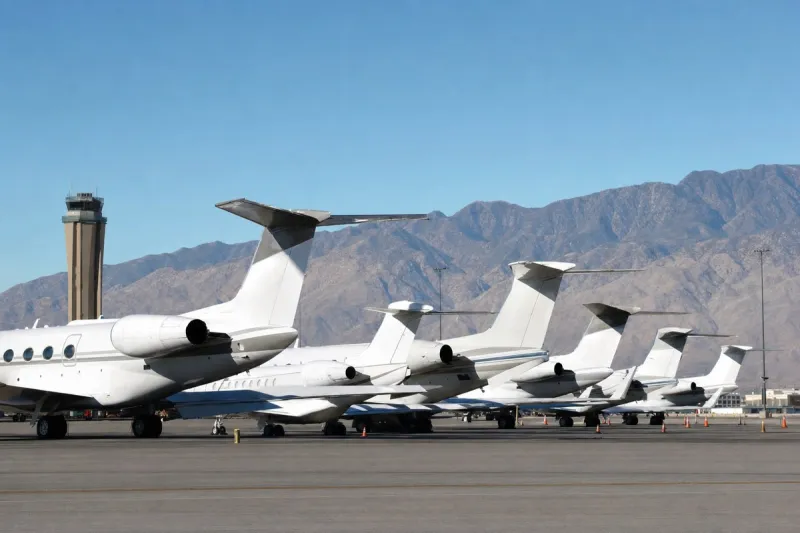
A blog survey of the Gulf Cooperation Council (GCC) business jet market lists the foreign manufacturers and service providers active there: Gulfstream Aerospace (US), Bombardier (Canada), Dassault Aviation (France), Textron Aviation (US), Embraer Executive Jets (Brazil), Boeing (US), Airbus Corporate Jets (EU), Pilatus Aircraft (Switzerland), VistaJet Group (Switzerland), Royal Jet (UAE), ExecuJet MRO Services (Switzerland/UAE), Jetex Flight Support (UAE), DC Aviation Al-Futtaim (UAE), Saudi Private Aviation (Saudi Arabia) and Qatar Executive (Qatar). No Japanese manufacturer appears among them.
Japanese business jet customers mainly buy aircraft from US, European and Brazilian manufacturers and commonly use operators and maintenance providers based in GCC countries. Middle Eastern operators help connect business demand between Japan and the GCC, and firms such as ExecuJet MRO Services and Jetex Flight Support provide supporting services to Japanese aircraft owners in some cases. Because Japan has a limited number of registered aircraft, service supply through these international networks is more common than direct transactions.
In the supplier comparison, Gulfstream, Bombardier, Dassault, Textron Aviation, Embraer, Boeing, Airbus Corporate Jets and Pilatus are described as offering advanced technology and high-quality aircraft, well regarded for long-range capability, comfort and safety, though generally at high prices. Regional suppliers such as VistaJet, Royal Jet and Qatar Executive are described as strong in maintenance and flexible operational support suited to the Middle East's harsh climate.
On the demand side, corporate globalization and the need for fast travel are cited, with manufacturing, finance and IT companies using business jets for executives' international meetings and site visits. Government bodies and local authorities are adopting them for emergency transport in disasters and VIP transfers, and the medical sector uses them for organ transplants and for sending doctors to remote areas. High-income users value privacy and avoiding crowded commercial airports, and the rise of charter and air taxi operators is making access more flexible.
Industry impact & what to watch
The supplier map described here shows how a regional business aviation market is typically layered: Western airframers at the top for aircraft supply, with Gulf-based operators and maintenance firms handling day-to-day operation and support. For a country with a small registered fleet, plugging into those international service networks is often more practical than building a domestic transaction base, which is consistent with the pattern of service supply outweighing direct sales in the Japan-GCC relationship described.
The split between premium manufacturers and regional operators also reflects how value is divided. Aircraft makers compete on range, comfort and safety at high price points, while operators and MRO providers compete on climate-suited maintenance and operational flexibility. Demand drivers that span corporate travel, government transport and medical missions suggest the customer base is broader than executive travel alone, which supports steady use of charter and on-demand services.
The piece is a market overview rather than a transaction announcement, so the practical test of its picture is whether the growth of charter and air taxi operators it points to translates into wider access for new users over time.