eVTOL Cash Burn Now the Key Variable Separating Joby Aviation and Archer Aviation
Why It MattersDivergent cash runways among eVTOL developers are becoming the key differentiator for certification-stage air-taxi companies, shaping which firms can time future capital raises from strength rather than necessity.
Joby Aviation and Archer Aviation, both deep inside the FAA certification process, are now being separated less by aircraft performance than by financial endurance. For the three months ending June 30, 2026, Joby closed with $2.3 billion in cash and short-term investments after raising roughly $1.2 billion through a combined equity and debt offering — about 52.9 million new shares at $11.35 each plus $600 million in convertible notes at 0.75 percent due February 2032. Joby reported a net loss of $245 million, including a large non-cash warrant revaluation charge, and an adjusted EBITDA loss of $197 million.
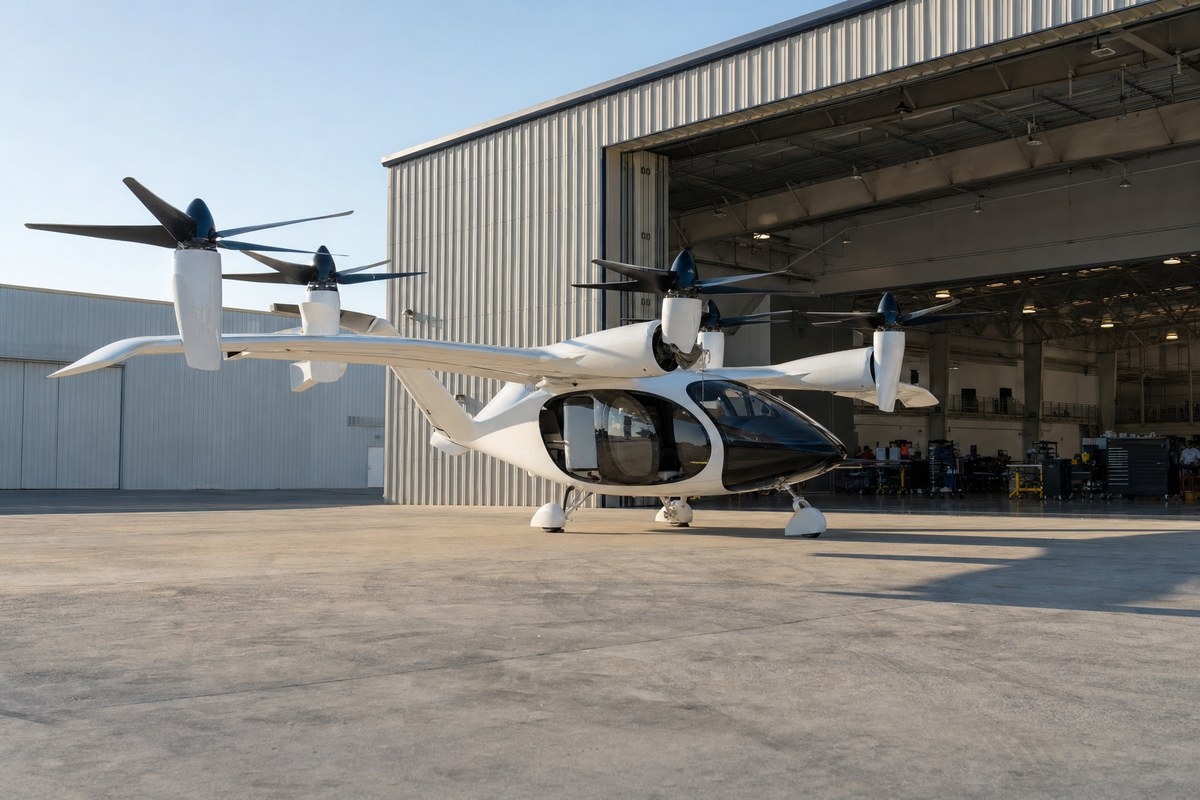
Archer reported a net loss of $263.2 million for the same period and an adjusted loss of $177.1 million. Excluding non-cash items, each company spends roughly $180 million per quarter on engineering, test operations and manufacturing. At that pace, Joby's reserves cover close to two years without further fundraising, while Archer said its existing liquidity should fund operations for at least the next twelve months, though it may need additional capital for long-term growth.
Lilium, a German eVTOL developer that raised more than one billion dollars before a rescue deal collapsed, ceased operations by early 2025 without certification or revenue. In contrast, China's EHang achieved record deliveries of its two-seat autonomous EH216-S in the final quarter of 2025 and reported its first quarterly profit in March 2026, largely from sightseeing and short-hop flights, while Shanghai-based Volant closed a Series C round exceeding $300 million in May 2026.
Archer has said it still expects to begin initial U.S. commercial operations in 2026. If revenue arrives before it needs to raise again, the cash gap with Joby narrows; if not, it faces selling equity into a market that has already absorbed its latest quarterly loss, while Joby retains more flexibility to time any future capital raise.