Japanese Suppliers in the Business Jet MRO Market: Strengths, Challenges and Outlook
Why It MattersThe outlook points to a widening split between OEM-affiliated MRO providers leveraging proprietary data and independents forced to specialise or adopt predictive-maintenance technology to compete.
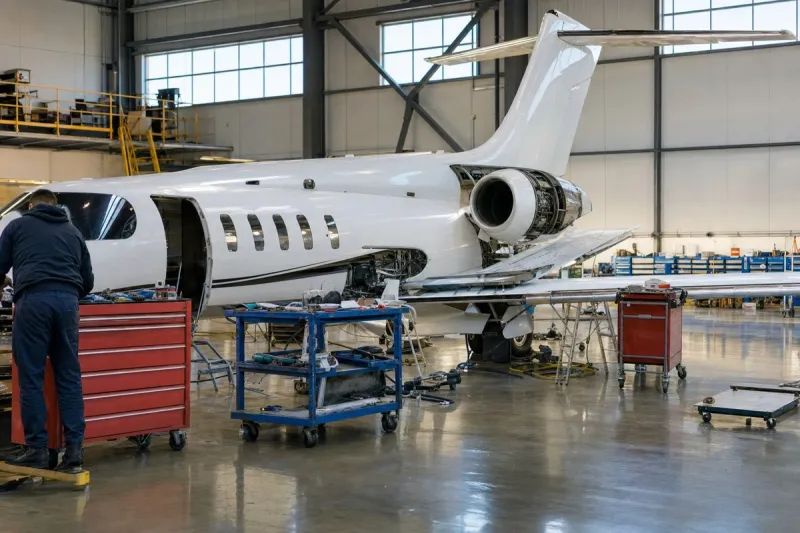
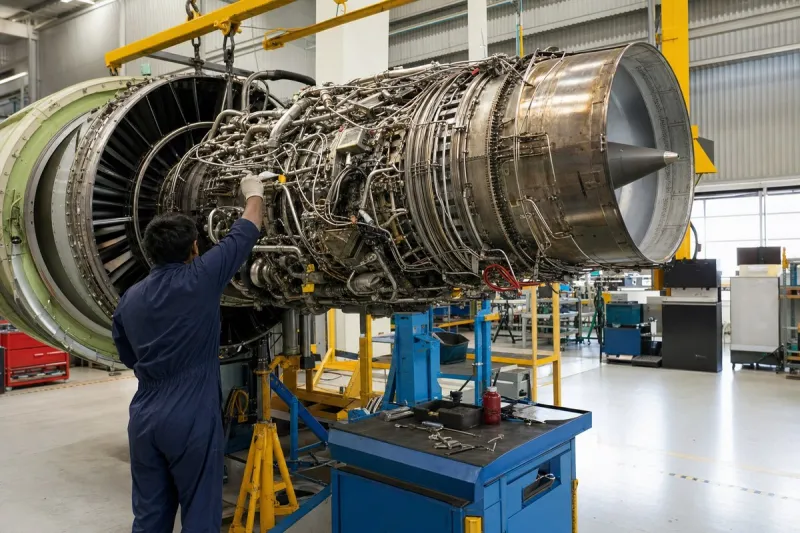
A market research blog post published on October 10, 2026 outlines the competitive position of Japanese suppliers in the global business jet MRO sector, naming major industry players including Bombardier Aviation, Gulfstream Aerospace Corporation, Dassault Aviation, Textron Aviation, Honeywell Aerospace, Rolls-Royce, GE Aerospace, Pratt & Whitney, Lufthansa Technik, Jet Aviation, Duncan Aviation, StandardAero, ExecuJet MRO Services, SR Technics, MRO Holdings, AAR Corp., Banyan Air Service, West Star Aviation, Falcon Aviation Services and TAG Aviation.
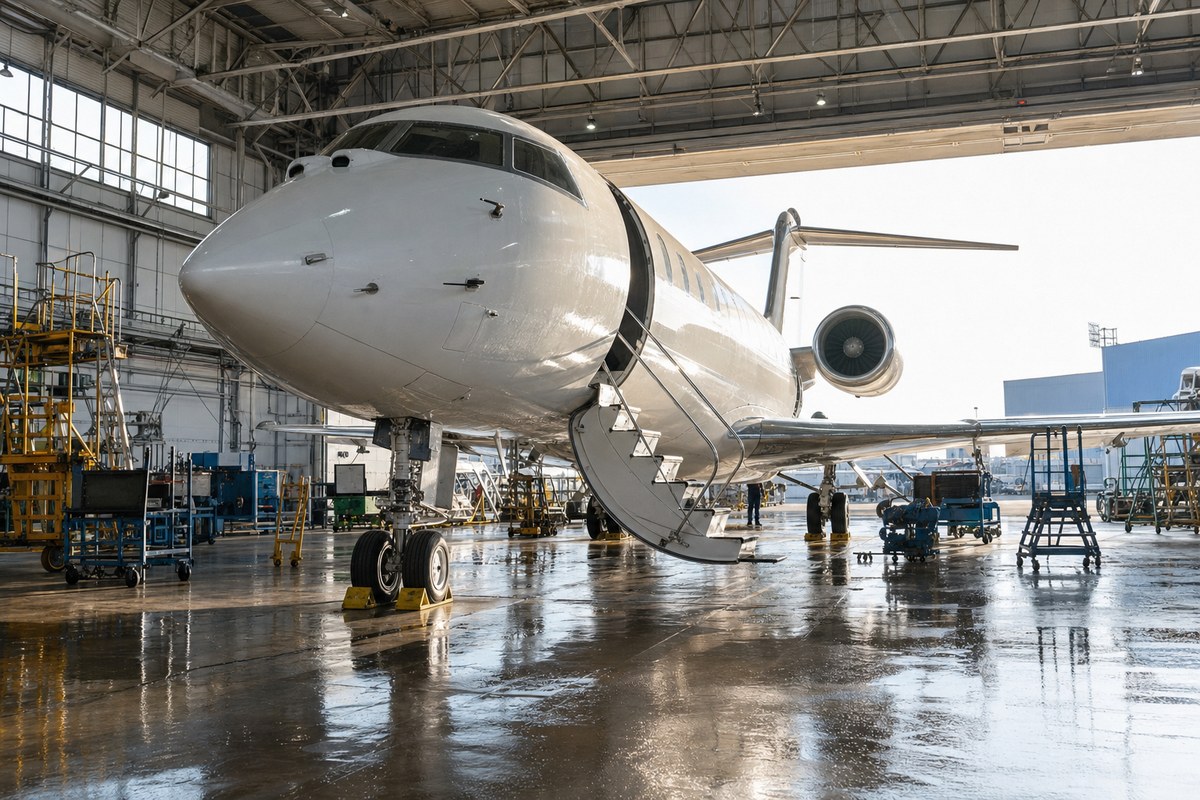
The post identifies Japanese suppliers' competitive strengths as precision machining, rigorous quality control, long-term customer relationships and advanced materials technology, including high-performance aluminium alloys, composite materials, and heat- and wear-resistant coatings. Japanese buyers are said to prioritise internationally certified quality management systems, robust local support, short parts lead times and custom-response capability when choosing suppliers.
Challenges cited include intense cost competition, pressure to shorten development cycles for new parts and modification kits, difficulty achieving economies of scale in inventory management, and the need to expand capacity in emerging markets such as Asia and the Middle East while maintaining quality standards, with smaller suppliers facing particular difficulty securing financing and skilled personnel.
Looking ahead, the post forecasts a deepening divide between OEM-affiliated MRO providers, expected to strengthen comprehensive maintenance contracts by leveraging proprietary aircraft data and parts supply chains, and independent MRO suppliers, which it argues will need to move away from pure price competition by specialising in specific aircraft types or modification areas and investing in digital predictive-maintenance technology, with expanded approval of third-party parts and Supplemental Type Certificates described as a potential differentiating opportunity.