Chartright Air Group Says Canada's Proposed Productivity Mega-Deduction Allows Full First-Year Write-Off of Eligible Aircraft
Why It MattersA first-year full deduction would move the cost case for owning a business jet toward tax timing, which tends to pull owner-operators and charter-revenue programs into the same purchase conversation.
What happened
Chartright Air Group, which describes itself as Canada's largest private jet charter provider, said on October 14, 2026, in Toronto that Prime Minister Mark Carney's recently announced Productivity Mega-Deduction could make business aviation more attractive to Canadian entrepreneurs and SME owners. Under the proposed measure, enterprises could deduct the full cost of an eligible aircraft in the year it becomes available for use, rather than depreciating it over several years under previous tax rules. A new or used aircraft, subject to the applicable rules, must have been acquired and be available for use to qualify.
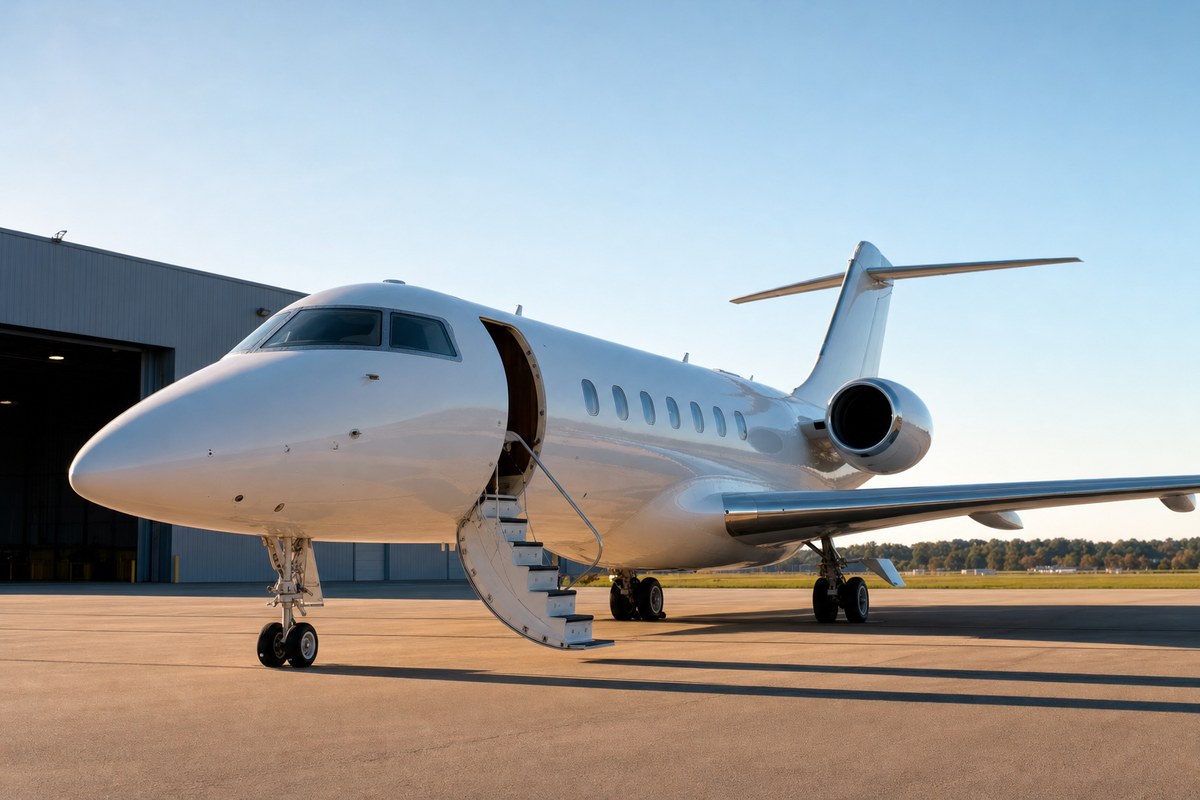
Chartright gave an illustrative example of an SME with C$95 million in revenue and C$20 million in taxable profit in a typical year. At a 26% corporate tax rate, that company would owe C$3.2 million in annual taxes. If it bought a C$10 million super-light or mid-size business jet, Chartright said, it could immediately reduce its federal taxes owing by C$2.6 million that year. Combined with modest charter sales through Chartright, annual operating costs could be as low as C$39,000 a month, the company said.
Ben Boehm, COO of Chartright Air Group, said the incentive is already generating market interest and that business aviation lets leaders meet clients face to face across Canada and the U.S. while saving time. Chartright cited an example of a Montreal-based SME owner flying to Toronto for a morning meeting, on to Winnipeg for a client dinner, and back to Montreal the same day. The company also highlighted its Charter Optimization Program, which gives aircraft owners revenue credits in advance to reduce their forecast annual operating costs, backed by 40 years of charter sales experience.
Industry impact & what to watch
Tax treatment sits near the front of most aircraft ownership decisions, and a measure that lets the full cost be deducted in the first year changes when the benefit arrives, not what the aircraft costs to operate. Charter providers with an owner-management or revenue-credit offer have an obvious interest in tying that timing benefit to ongoing operating economics, which is the pairing Chartright put forward in its own example.
The figures in that example are the company's illustration for one hypothetical SME, and the measure is described as proposed. The point to follow is how the final rules define an eligible aircraft and when it must be available for use, since those conditions decide which buyers, new or used, can actually claim the deduction.