Ten Aviation Insurance Brokers Serving Aircraft Owners and Operators in 2026
Why It MattersAviation insurance capacity is bifurcating by segment, with well-managed general aviation risk attracting competition even as airline losses, geopolitical exposure and war-risk wording draw tighter underwriting scrutiny elsewhere.
What happened
A 2026 review covers ten aviation insurance brokers ranging from global insurance groups to specialist aviation-focused brokerages, serving private aircraft owners, charter operators, airlines, FBOs, MROs and aerospace companies across hull, liability, war risk and other aviation exposures.
Marsh Aviation & Space runs a global specialist practice for airlines, aircraft owners, airports, lessors and manufacturers, extending into risk modelling, claims and programme design alongside placement. Aon's Global Aviation Practice includes more than 120 aviation specialists globally, covering hull and liability, hull war, excess war liability, products liability, airport risks and specialist cover for lessors and financial institutions. WTW Aviation & Space serves airlines, private owners, airports, MROs and manufacturers, combining placement with analytics and published market reports on airline, general aviation, aerospace and lessor insurance. Gallagher's Aerospace and Aviation practice spans commercial aviation, general aviation, airports and aerospace, with claims consultancy, risk management and dedicated general aviation capabilities for owners and pilots.
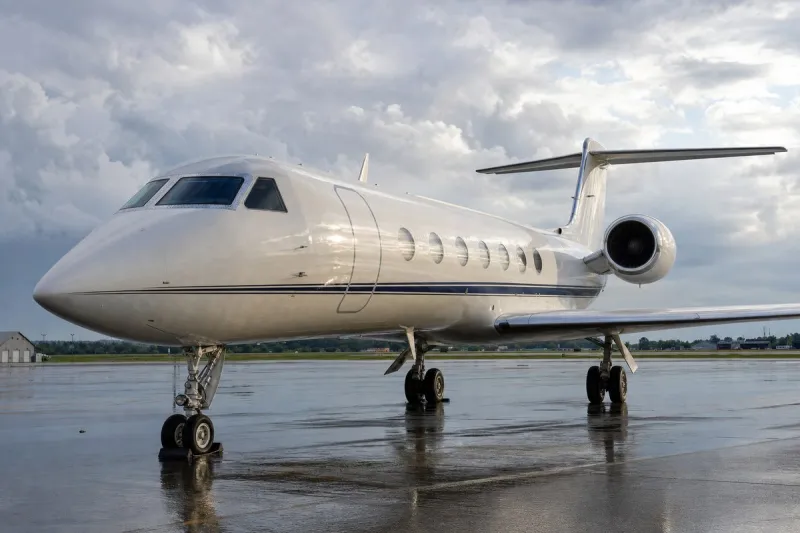
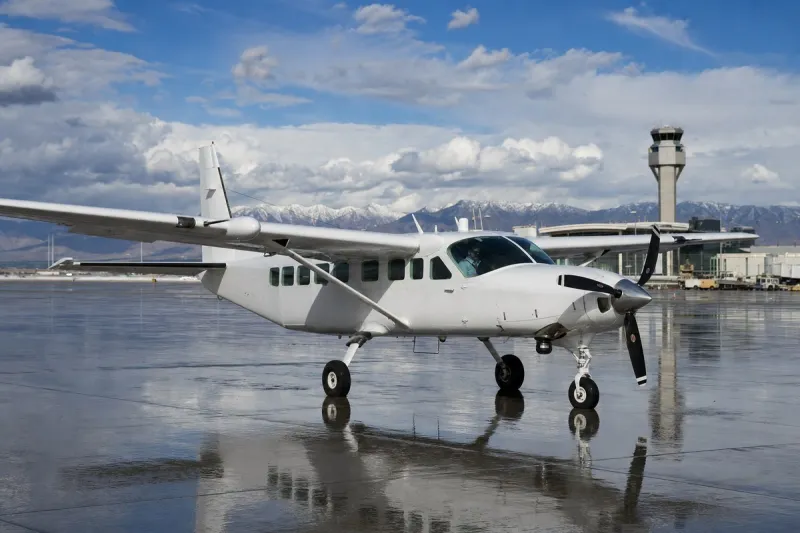
Howden Aviation & Aerospace has grown to more than 70 aviation specialists across international markets and launched a dedicated US Aviation Practice in 2026, covering airlines, private aviation, FBOs, airports, manufacturers and MRO companies. Lockton Aviation covers airlines, private operators, manufacturers, airports and service providers with hull, liability, war risks, crew loss of licence, product liability and overhaul and repair facility cover. HUB International serves private aircraft owners and corporate and commercial clients with hull and liability, non-owned liability, hangarkeepers, premises liability, workers' compensation and acquisition risk advice. McGriff's Aviation & Aerospace practice covers corporate aviation, commercial operators, FBOs, cargo operations and managed fleets, including hull and liability, products liability, war cover, cyber, pollution, cargo and management liability. Falcon Insurance Agency, a US-based brokerage founded in 1979, focuses exclusively on aviation insurance for personal aircraft, business jets, commercial aircraft, rotorcraft, drones and specialist risks, with offices across the United States. BWI Aviation Insurance, another US specialist brokerage, focuses on aircraft owners, pilots and aviation businesses, covering private jets, piston aircraft, turboprops, helicopters, charter operations, maintenance businesses, flight schools and hangars, working with major US underwriting markets.
Market conditions
Capacity remains available across much of the aviation insurance market in 2026, though underwriting conditions differ significantly by segment. Well-managed general aviation risks continue to attract competition among insurers, while airline losses, geopolitical exposure and higher claims costs are creating greater underwriting scrutiny elsewhere. War-risk wording has become increasingly important for operators flying in regions affected by geopolitical instability.
Industry impact & what to watch
The presence of both diversified global brokers and narrow aviation specialists in the same review reflects how placement in this segment splits between firms that bundle aviation into a broader risk practice and those built exclusively around aircraft exposures. Scale matters differently depending on the client: a global lessor or airline draws on a broker's cross-border claims and risk-modelling bench, while an owner-operator or flight school is better served by a specialist with direct underwriter relationships in a narrower niche.
The segment's underwriting cycle is running in two directions at once. Capacity chasing well-managed general aviation risk keeps pricing competitive for owners and operators with clean records, while airline-scale losses and geopolitical exposure push insurers toward tighter terms and more scrutiny in the segments most exposed to those risks. War-risk wording is becoming a distinct line item rather than boilerplate, which signals insurers are pricing geographic exposure more explicitly than before.
What moves next is whether the divergence between general aviation and airline/geopolitical risk pricing widens or narrows as claims costs develop through the underwriting year, and whether brokers expanding specialist teams, such as the new US-focused practice launched in 2026, translate added headcount into broader market access for clients.