FAA Convenes Airlines, Investors to Explore Private Capital for Airport Development
Why It MattersAs grant funding stays capped and privatization participation stays minimal despite eased 2018 rules, airport capital planning increasingly depends on how regulators define private investment's supplementary role.
What happened
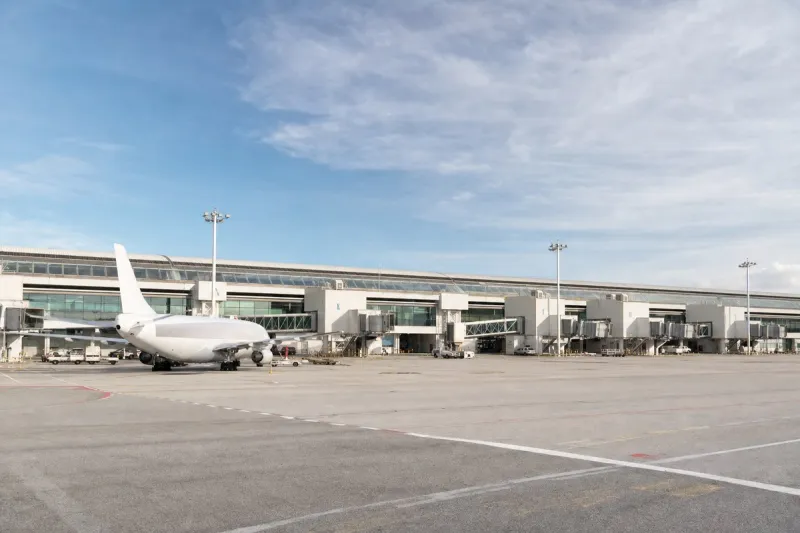
The Federal Aviation Administration held a daylong event in Washington on Tuesday bringing together airport executives, airlines, operators, and investment firms to examine how private capital could supplement traditional funding for airport development, with a focus on small and medium-hub airports. The agenda included discussions with investors from BlackRock, Carlyle, Apollo, Goldman Sachs, and other firms, alongside airport sponsors and airline representatives, with FAA officials addressing existing funding programs and the regulatory requirements that apply when private money is used for airport projects.
Traditional federal grants and airport-generated revenue remain the primary sources of airport capital. In August, the FAA awarded nearly $615 million through the Airport Improvement Program for runway, taxiway, terminal, and other projects at more than 100 airports nationwide, including numerous general aviation facilities. Tuesday's discussions focused on where private capital could supplement those existing sources and what regulatory or policy changes may be needed to encourage additional private investment.
The FAA also operates an existing privatization program that allows public airport sponsors to sell or lease airports to private operators under certain conditions. Congress removed limits on the number and types of participating airports in 2018, but participation has remained limited: as of February, only Luis Muñoz Marín International Airport in Puerto Rico and Hendry County Airglades Airport in Florida were listed in the program. Tuesday's event was described as broader than outright airport privatization, examining ways private capital could play a supplementary role in airport infrastructure.
Industry impact & what to watch
This gathering signals that federal policymakers see a gap between what grant programs and airport revenue can cover and what small and medium-hub airports actually need for runway, taxiway, and terminal work. The $615 million August award, spread across more than 100 airports, illustrates how thinly the existing Airport Improvement Program stretches when divided among that many projects.
Airport capital has historically run on a narrow set of channels: federal grants, passenger facility charges, bonds backed by airport revenue, and, for a small number of sponsors, outright sale or lease to a private operator. That last channel has stayed nearly unused since Congress lifted participant caps in 2018, with only two airports listed as of February, which is presumably why Tuesday's conversation was framed around a supplementary role for private capital rather than a repeat of the privatization pitch.
What happens next depends on whether the FAA follows this event with concrete regulatory or policy proposals addressing how private capital can be layered onto existing funding without triggering the same participation problems that have limited the privatization program. Any such proposal, and the reaction from airport sponsors and the investment firms in the room, would be the next marker worth watching.