Textron (NYSE: TXT) Trades at $86.26 with Moderate Buy Consensus and 18.8% Upside Target
Why It MattersDiversified aerospace-and-defense manufacturers can trade at a discount to broad-market multiples even while posting revenue growth and earnings beats, reflecting segment mix rather than weaker fundamentals.
What happened
Textron Inc., based in Providence, Rhode Island, traded at $86.26, down about 1.0% from its $87.13 opening price at the start of 2026. Analysts have assigned the stock a consensus rating of Moderate Buy, comprising 1 strong buy, 3 buy, and 6 hold ratings, with a consensus price target of $102.44, implying approximately 18.8% upside from the current price.
For the second quarter ended July 28, 2026, Textron reported earnings per share of $1.62, beating the analyst consensus estimate of $1.55 by $0.07. Quarterly revenue rose 3.0% year over year. Full-year earnings are expected to grow 12.62%, from $6.50 to $7.32 per share. The stock carries a price-to-earnings ratio of 16.28, below the broad market average of approximately 39.61 and the industrials sector average of 26.79. Its PEG ratio is 1.29 and price-to-book ratio is 1.91. The dividend yield is 0.09%, with a payout ratio of 1.51%.
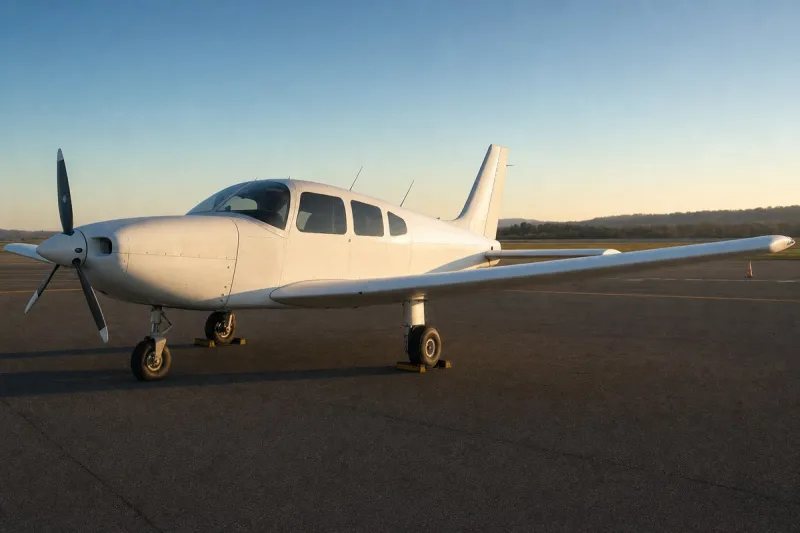
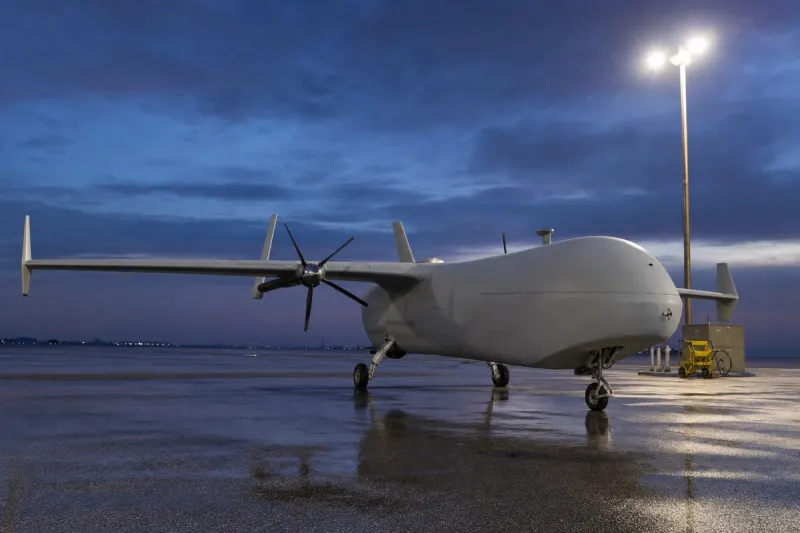
Institutional investors hold 86.03% of Textron shares, with BlackRock Inc. the largest institutional holder at 9.09%. Insiders hold 1.90% of shares, and no insider buying or selling has been reported in the past three months. Textron, founded in 1923, operates through four segments: Textron Aviation, covering Cessna and Beechcraft aircraft; Bell, covering commercial and military rotorcraft; Textron Systems, covering unmanned systems and defense products; and Industrial, covering E-Z-GO and Arctic Cat vehicles. Scott C. Donnelly is President and CEO.
Industry impact & what to watch
A conglomerate spanning business jets, military and commercial rotorcraft, defense systems and industrial vehicles gets valued by the market as a blend of those cycles rather than on any single segment's outlook. Textron's price-to-earnings ratio sitting well below both the broad market and the industrials sector suggests investors are pricing in slower growth or cyclicality somewhere in the mix even as consolidated earnings beat estimates.
This is how diversified aerospace holding companies typically trade: a discount to peers can persist even through a quarter of revenue growth and an earnings beat, because the market is weighing the combined trajectory of aircraft deliveries, rotorcraft orders, defense contracts and consumer vehicle demand rather than any one of them in isolation.
The next full-year results will show whether the projected move from $6.50 to $7.32 in earnings per share materializes, and whether analysts move the consensus price target or rating mix in response to how each of the four segments performs individually.