Delaware Aircraft Purchases Carry No Sales or Use Tax, State Among Only Five Nationwide
Why It MattersBuyer-state tax exemptions can shift closing location decisions even when nonresident fly-away rules do not apply, since escrow, title search, and financing remain centralized nationally regardless of where delivery occurs.
What happened
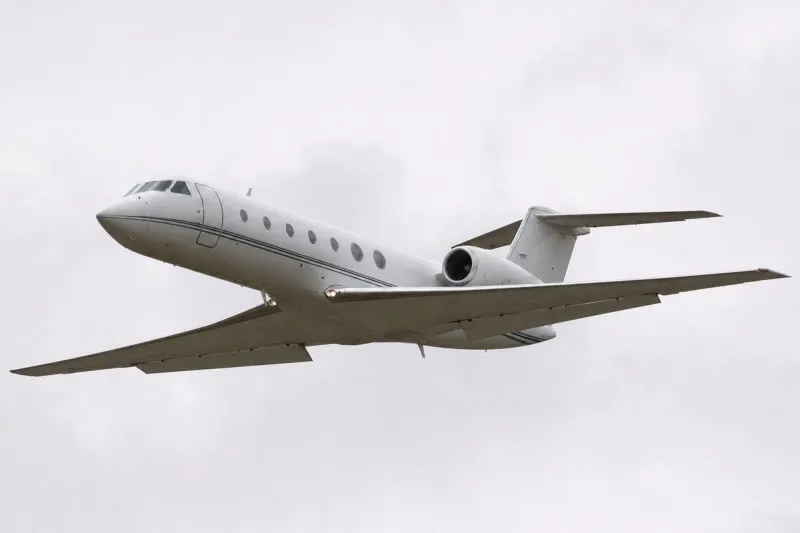
Delaware imposes no state or local sales tax and no use tax on aircraft purchases, placing it among only five U.S. states with a complete absence of such levies. An aircraft purchase closed and delivered in Delaware owes no sales or use tax regardless of purchase price, aircraft type, or buyer residency.
A separate gross receipts tax applies to sellers who are in the business of selling aircraft, not to buyers. Aircraft with a maximum takeoff weight of 12,500 pounds or more are exempt from that gross receipts tax outright, and an isolated sale by a private seller not in the aircraft business is not taxed at all. Because the gross receipts tax is a seller-side obligation, it is not itemized to the buyer at closing. Delaware does not offer a nonresident fly-away exemption in the traditional sense; because no sales or use tax exists, any buyer — resident or nonresident — can take delivery in Delaware without sales-tax exposure.
On federal bonus depreciation, Delaware only partially conforms to federal treatment. The state requires an addback of bonus depreciation for personal income tax purposes and has decoupled its corporate income tax from the 2025 federal restoration of 100 percent bonus depreciation for property placed in service after January 19, 2025.
Delaware's aviation economy centers on New Castle Airport (ILG) near Wilmington and Summit Aviation, an aircraft maintenance and modification specialist based in Middletown. A 2018 Delaware Department of Transportation-sponsored study found the state's public airports support more than 12,000 jobs and generate over $1.1 billion in annual economic impact statewide.
How the closing process works
All U.S. aircraft closings, including those involving Delaware buyers, are conducted through an FAA escrow agent in Oklahoma City, where title is searched and documents are filed with the registry on funding day. Financing terms are set nationally by aircraft type, credit profile, and loan structure rather than by state of residence.
Industry impact & what to watch
Delaware's position belongs to a small group of states competing for aircraft transaction activity through the absence of transfer taxes rather than through targeted fly-away carve-outs. Where most states with sales tax exposure build a nonresident exemption to keep closings from migrating elsewhere, Delaware's blanket exemption makes that carve-out unnecessary, since resident and nonresident buyers face identical treatment at closing.
The seller-side gross receipts tax and the weight-based exemption for aircraft at or above 12,500 pounds mean the tax question buyers actually face is narrower than a simple state-tax comparison suggests: private isolated sales and larger aircraft transactions both fall outside the levy entirely, leaving it relevant mainly to dealers selling smaller aircraft. The partial decoupling from 100 percent federal bonus depreciation is a separate variable that a buyer's tax advisor has to model alongside the sales-tax picture, since it applies differently to personal and corporate income tax filers.
Because closing mechanics run through a national FAA escrow process in Oklahoma City regardless of where delivery happens, state tax treatment affects where a deal is booked without changing how the underlying transaction is documented or financed. What remains to be seen is whether Delaware's aviation-economy figures, drawn from a 2018 study, are updated to reflect current activity at New Castle Airport and Summit Aviation.