How Aircraft Sellers Can Prepare for a Pre-Purchase Inspection
Why It MattersPre-purchase inspection practices show that transaction risk in aircraft sales is managed less through the inspection itself than through upfront agreement on scope, cost and how discrepancies get resolved.
What happened
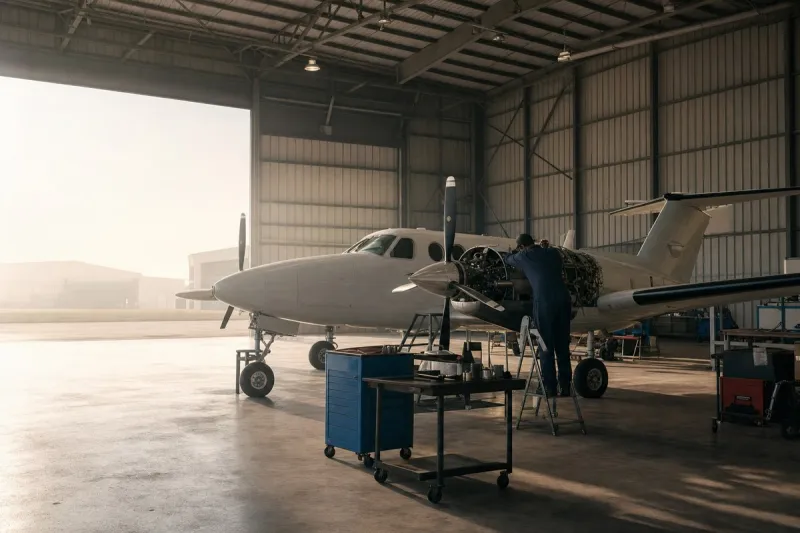
Guidance issued on preparing for a pre-purchase inspection outlines steps sellers can take before a buyer's inspector examines an aircraft. The inspection is conducted primarily for the buyer's benefit, but sellers who prepare can reduce avoidable delays and surprises during the process.
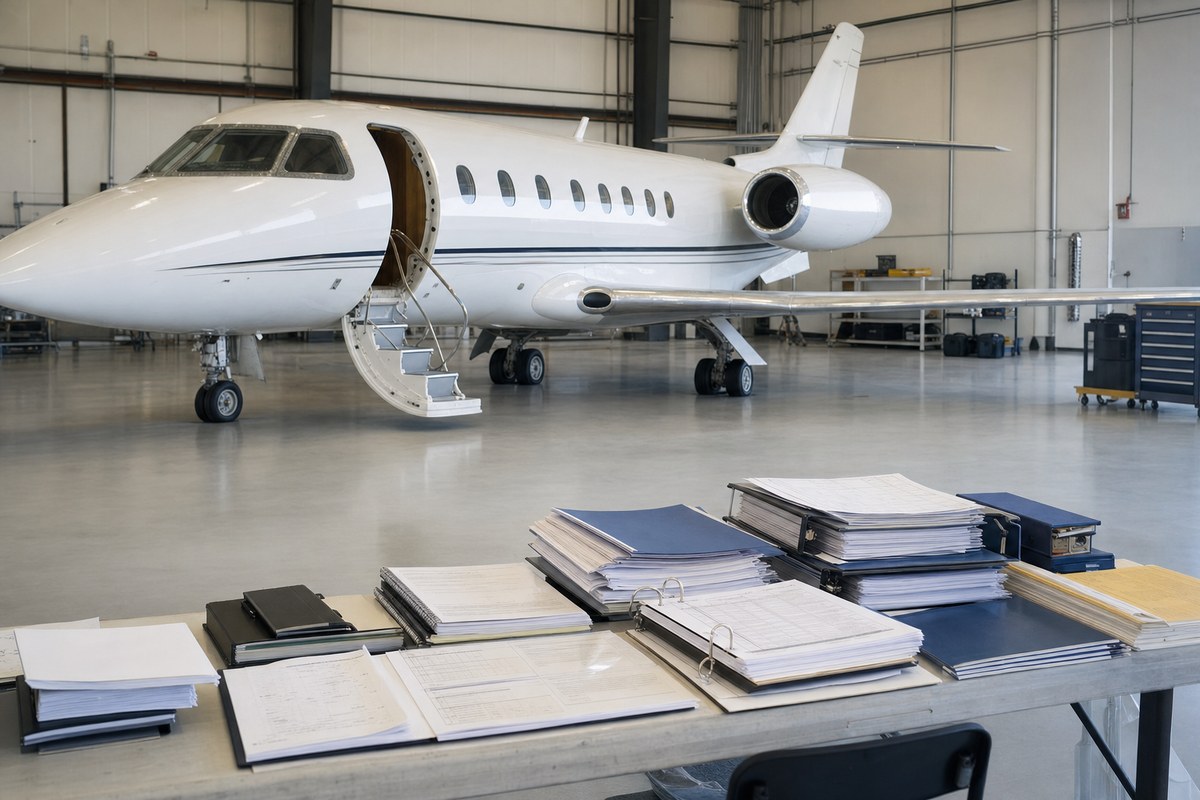
Recommended steps include organising logbooks and maintenance records, gathering documentation for all repairs and modifications, reviewing known defects and disclosing them appropriately, confirming that maintenance and component status is current, ensuring all agreed equipment is with the aircraft, and making certain the aircraft is clean and accessible. Sellers are advised not to attempt to influence the buyer's inspector or conceal defects, and the buyer should be free to select an appropriately qualified independent professional and to assess the aircraft's condition independently.
Both parties are also advised to agree in advance on the scope of the inspection, who bears the associated costs, and how significant discrepancies will be handled if they are discovered.
Industry impact & what to watch
This guidance points to a recurring feature of aircraft sales: the pre-purchase inspection is where disclosed condition meets independent verification, and gaps between the two are where deals stall or collapse. Organised records and disclosed defects narrow the space in which an inspector can surface something unexpected.
The advice to fix scope, cost allocation and a discrepancy-resolution process before the inspection begins reflects how these transactions actually work in practice: the inspection itself is a fixed technical exercise, but the commercial risk sits in what happens after a finding is made, not in the finding itself.
What determines whether a transaction proceeds smoothly is whether buyer and seller have already agreed, in writing, how a significant discrepancy gets handled once the inspector reports it.