FTAI Aviation (FTAI) Secures New Financing, Is It Still 12% ...
Why It MattersFinancing capacity built around aging narrowbody fleets and scarce engine supply is becoming a distinct funding channel, separate from traditional new-aircraft leasing.
What happened
FTAI Aviation has closed a new $2.0 billion warehouse financing facility for its 2026 special purpose vehicle, giving the company fresh capital to acquire on-lease, mid-life 737NG and A320ceo aircraft.
The company's share price is down 21.5% over the past 90 days, while the one-year total shareholder return stands at 36.5%; the five-year total shareholder return remains substantial. According to the most widely followed valuation narrative on FTAI Aviation, the stock's fair value is estimated at $225.05 compared with a recent close of $197.81, framing the pullback as a discount of approximately 12.1%. A separate valuation approach puts the company's current price-to-earnings ratio at 42.5 times against a peer average of 21.9 times and a fair ratio of 61 times.
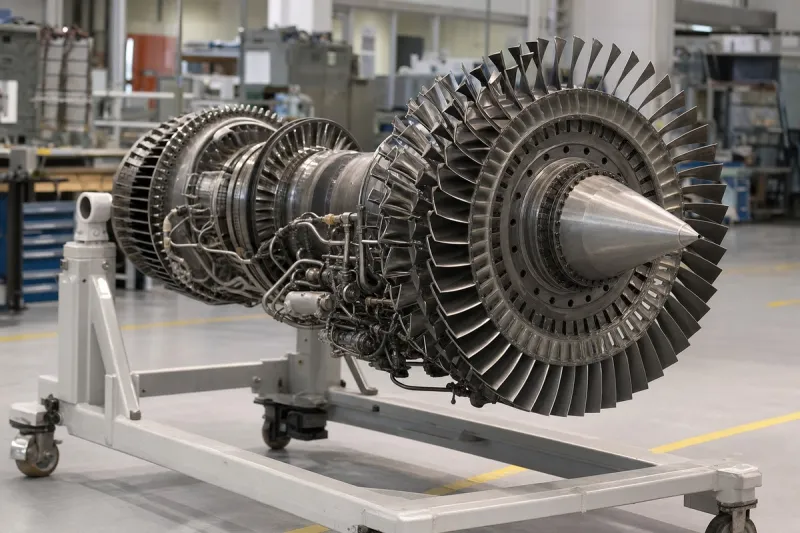
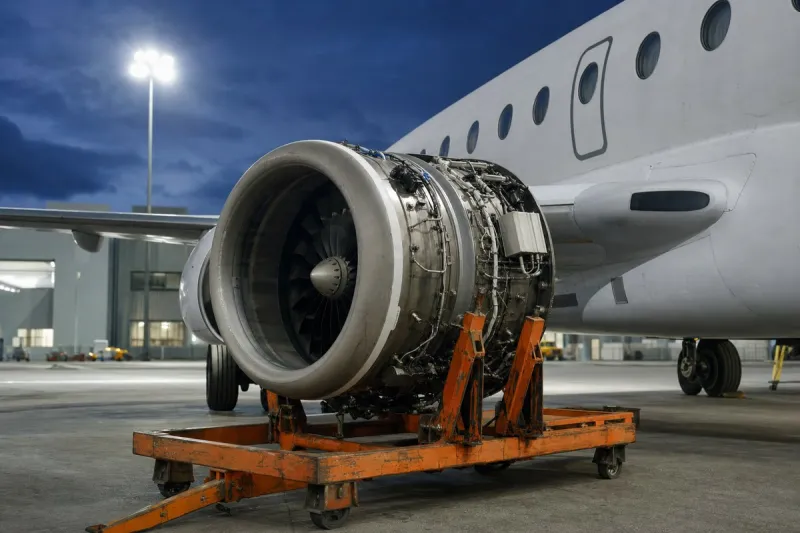
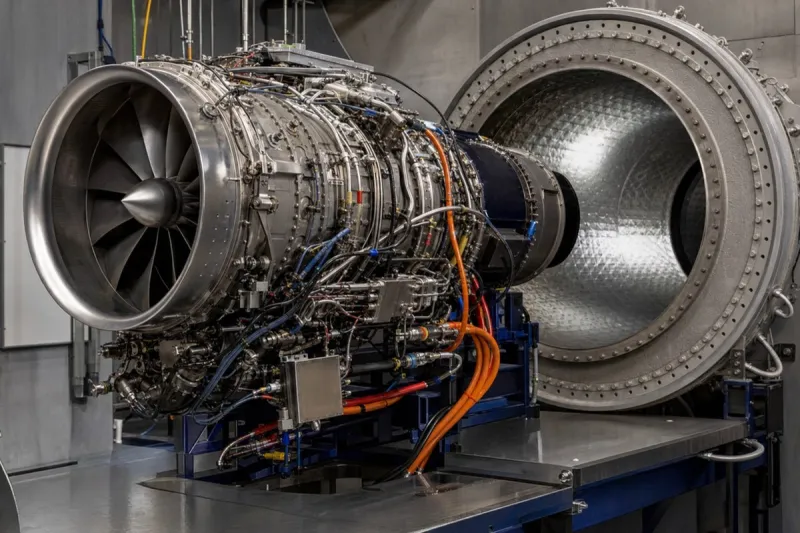
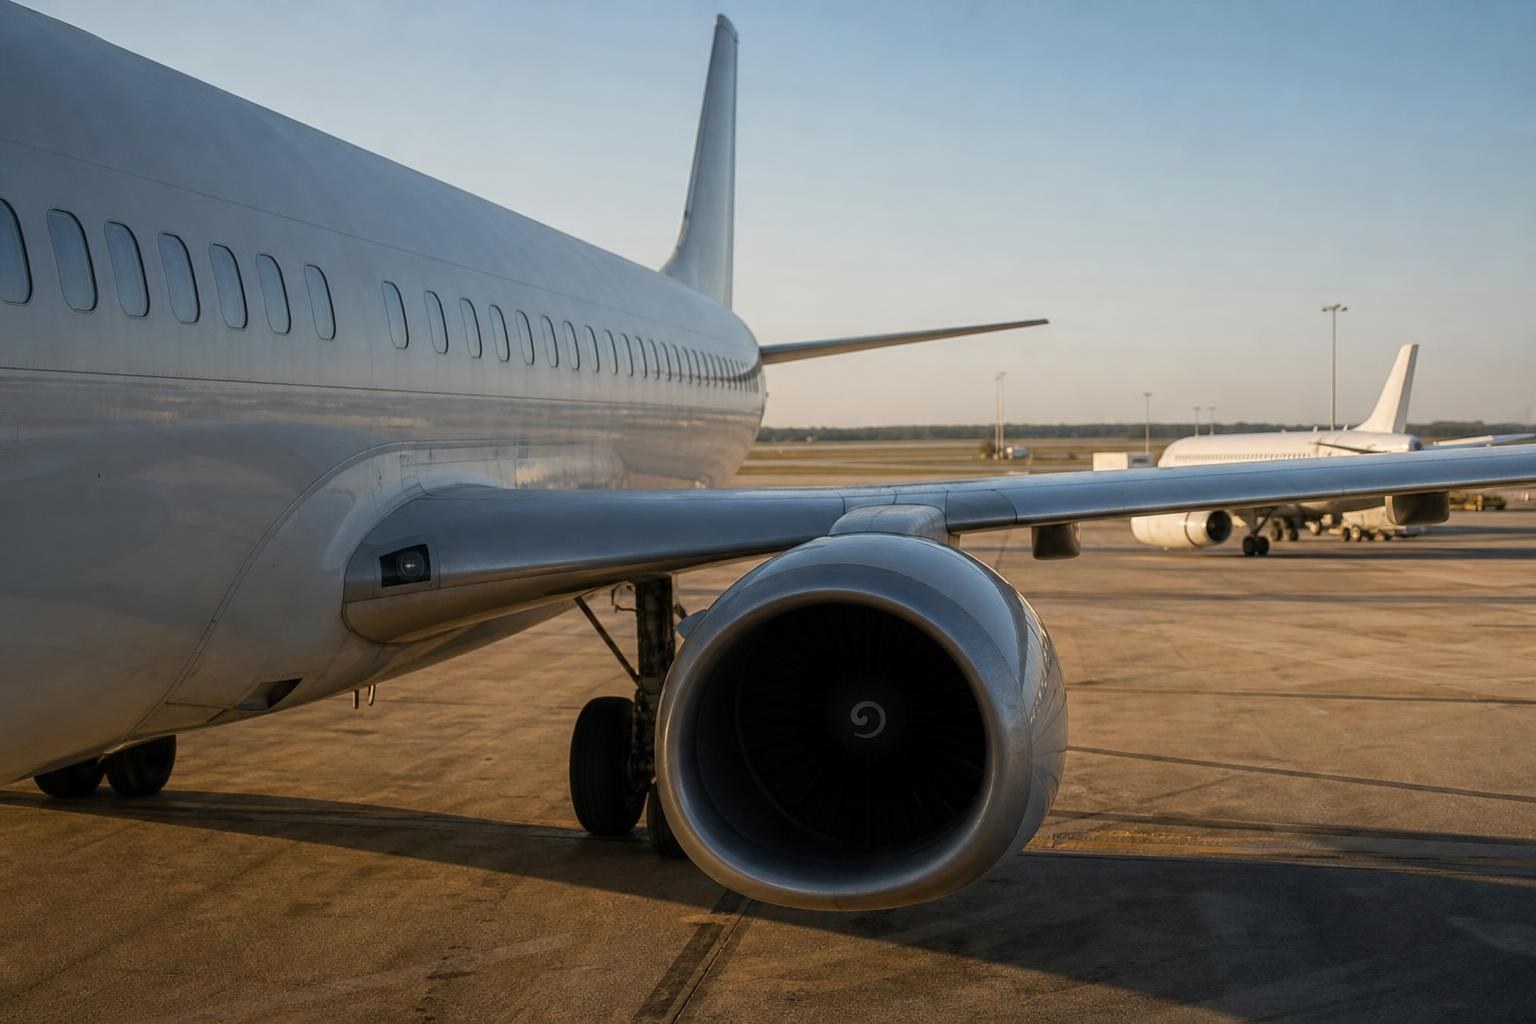
FTAI Aviation's portfolio carries concentrated exposure to aging CFM56 and V2500 engines, alongside a leveraged balance sheet that relies on supportive financing conditions. The company describes itself as evolving into a hybrid aerospace infrastructure and aftermarket platform, citing structural tailwinds, an integrated business model and aftermarket margins as strengths, while naming leverage, concentration and execution complexity as key risks.
Industry impact & what to watch
Warehouse facilities of this kind let a platform stockpile capital ahead of acquisitions rather than raise financing deal by deal, which matters most when the target assets are older airframes carrying engines already in short supply. Structuring that capital around a 2026 special purpose vehicle signals an acquisition pipeline extending into next year rather than a one-off purchase.
The investment case FTAI Aviation is being valued on rests on two conditions holding: aging-fleet economics that keep 737NG and A320ceo aircraft valuable for parts and leasing, and continued engine shortages that support the pricing FTAI can charge on CFM56 and V2500 work. A leveraged balance sheet means that case is more sensitive to financing costs than a lessor with less debt would be.
The valuation split described here is itself worth watching: one approach puts fair value only modestly above the recent close, while the price-to-earnings comparison implies the market is pricing in far more growth than peers receive. Whether the 90-day share price decline reflects a re-rating toward the more conservative estimate, or a temporary dislocation from the one-year return, will depend on how the acquisitions funded by this facility perform once deployed.